
What Is an Estate Freeze? A Simple Guide for Owners
Discover what an estate freeze is, how it works, and why business owners use it to lock in today’s value and pass future growth to the next generation.

Discover what an estate freeze is, how it works, and why business owners use it to lock in today’s value and pass future growth to the next generation.

Most people buy life insurance for one reason: to make sure their family is protected if something happens to them. But there is a type of life insurance that does something more – it builds value over time while you are still alive. That type is called participating whole life insurance, and it works very differently from the term policies most Canadians are familiar with.
Here is what it means, how it works, and whether it might be a fit for you.
Term life insurance covers you for a set period – 10, 20, or 30 years. Participating whole life insurance is permanent. It covers you for your entire life, as long as premiums are paid, and the death benefit is guaranteed.
That permanence is the first major difference. But the bigger difference is what happens to your premiums while you are alive.
With a term policy, your premiums go entirely toward the cost of insurance. With participating whole life, the insurer pools premiums into a participating account that is professionally managed. Dividends may be paid when the account’s experience is favourable, based on factors such as investment returns, expenses, and mortality experience.
The word “dividend” here is different from stock dividends. In the context of a participating whole life policy, a dividend is a share of the insurance company’s surplus – essentially, the company returning a portion of the money when investment performance, claims experience, and expenses go better than expected.
These dividends are not guaranteed. They are declared each year by the insurance company based on how the participating account performed. That said, many Canadian participating insurers have long histories of paying dividends, though past performance does not guarantee future results.
When you receive a dividend, you have a few options for how to use it:
Take it as cash. The dividend is paid to you directly.
Apply it to your premium. It reduces how much you pay out of pocket.
Buy additional paid-up insurance. This is the most common choice. The dividend purchases more coverage, which in turn earns its own dividends. Over time, this compounds.
Leave it on deposit. The dividend sits with the insurer and earns interest.
Most policyholders who hold participating whole life for the long term choose to purchase additional paid-up insurance, because it accelerates both the death benefit and the cash value of the policy.
One of the most distinctive features of a participating whole life policy is that it builds cash value. The policy builds guaranteed cash value as part of its structure, and dividends can add a non-guaranteed layer of growth if they are used to buy paid-up additions.
The policy accumulates cash value that you may be able to access, subject to policy terms, in a few ways:
Policy loans. You can borrow against the cash value without going through a lender or credit check. Policy loans do not have fixed repayment schedules, but any unpaid balance can reduce the death benefit.
Surrendering the policy. If you decide you no longer need the coverage, you can cancel the policy and receive the accumulated surrender value. The tax treatment on surrender can be technical and depends on the policy’s adjusted cost basis — the disclaimer at the end of this article applies here.
The cash value grows on a guaranteed basis, separate from the dividends. The dividends, if used to purchase paid-up additions, add a non-guaranteed layer of growth on top.
Participating whole life is not the right fit for every situation. Because premiums are higher than term insurance, it is most commonly used by people who have a long-term need for life insurance and who can sustain the premium over time.
Some of the most common situations where it makes sense:
Families building long-term wealth. For parents who want to ensure a guaranteed death benefit no matter when they pass, plus build a tax-advantaged asset over decades, participating whole life offers both.
Business owners and incorporated professionals. A participating whole life policy held inside a corporation may offer a tax-efficient approach to building cash value inside a permanent policy, depending on the structure and the corporation’s specific situation. It can be used by incorporated professionals – such as dentists and physicians – to redirect excess corporate cash into a long-term, protected asset.
Estate planning. For those who want to leave a specific, guaranteed sum to their heirs or a charitable organization, a participating whole life policy creates a known outcome – the death benefit- regardless of when death occurs.
High net worth individuals. When other registered accounts (TFSA, RRSP) are maximized, participating whole life can offer a tax-efficient way to build cash value inside a permanent policy, outside of registered limits.
Term and participating whole life insurance are not competitors- they serve different purposes, and many Canadians use both at different stages of life.
Term insurance is a straightforward, affordable way to protect your family during the years it matters most – while a mortgage is being paid down, while children are young, or while income replacement is the primary concern. It does exactly what it is designed to do.
Participating whole life steps in when the need for coverage is permanent, when building long-term cash value matters, or when the policy is part of a broader estate or corporate strategy. The two products often complement each other well, and choosing one does not mean ruling out the other.
Participating whole life insurance combines permanent death benefit protection with a growing cash value and the potential for dividends. It is a longer-term commitment with higher premiums, and it is designed for situations where permanence, cash value, and legacy planning are part of the picture.
If you are considering permanent life insurance, take time to review how dividend performance has held up at the insurer you are looking at, understand the various dividend options, and think through whether the long-term commitment fits your situation.
This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such. Policy design, dividend scale performance, cash value growth, and tax treatment vary by insurer and by the specific policy contract. Always review the policy illustration and contract terms carefully.
Sources:

The deadline for filing your 2025 income tax return is April 30, 2026. With several changes this year, from a lower federal tax rate to new benefits and eliminated credits, it pays to know what has changed before you file. This guide covers the key updates, deductions, and credits separated into sections for Individuals and Families, and Self-Employed Individuals.
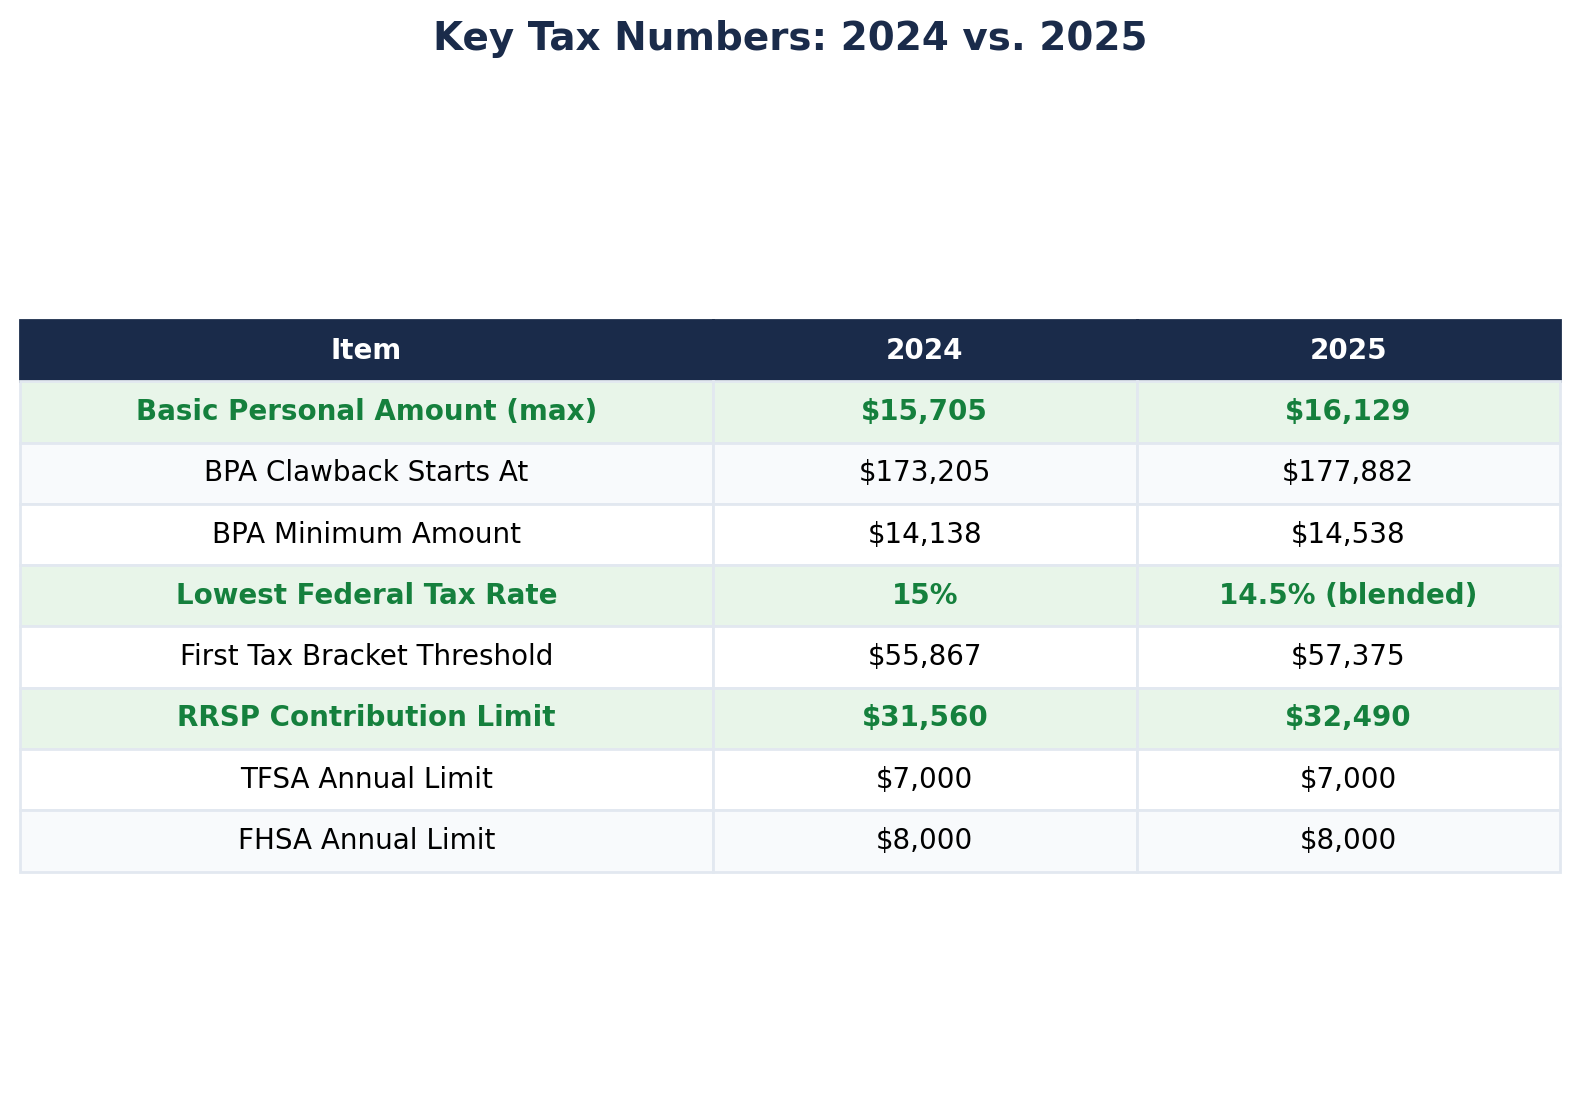
Effective July 1, 2025, under draft legislation introduced May 27, 2025, the lowest federal income tax rate was reduced from 15% to 14%. Because this change took effect halfway through the year, the blended rate for 2025 is 14.5%. This applies to the first $57,375 of taxable income and could save an individual up to $420 per year, or up to $840 for a two-income household.
Because the lowest rate also determines the value of most non-refundable tax credits, the government introduced a new top-up credit. This credit restores the full 15% value on eligible non-refundable credits claimed on amounts above $57,375, so the rate cut does not reduce the value of credits like the Basic Personal Amount, medical expenses, or tuition. This top-up credit will remain in place through the 2030 tax year.
For 2025, the Basic Personal Amount has increased to $16,129 for taxpayers with net income up to $177,882. For those with net incomes above this amount, the BPA is gradually reduced, reaching a minimum of $14,538 at incomes of $253,414 or higher.
The proposed increase in the capital gains inclusion rate from 50% to 66.67% on gains over $250,000 for individuals (and on all gains for corporations and most trusts) has been cancelled. The inclusion rate remains at 50% for all taxpayers. However, the lifetime capital gains exemption has been raised to $1,250,000 for qualifying dispositions of small business shares and farming or fishing property, up from $1,016,836.
A new benefit became available in June 2025, providing up to $200 per month ($2,400 per year) for Canadian residents aged 18 to 64 who are approved for the Disability Tax Credit.
The benefit is income-tested, with the maximum amount generally available to single individuals with adjusted family net income of $23,000 or less. For couples, the threshold is higher (generally $32,500 after a working income exemption).
The benefit is gradually reduced as income increases. For single individuals, it is typically reduced by 20 cents for each dollar above the threshold. For couples, the reduction may be 20% or split at 10% each, depending on whether one or both partners qualify for the benefit.
Canadian Journalism Tax Credit: The 15% non-refundable tax credit for qualifying digital news subscriptions (up to $75 per year) is no longer available for 2025.
Home Accessibility and Medical Expense Double-Claim: Under proposed measures announced in Budget 2025 and included in Bill C-15, 2025 is expected to be the final year that certain expenses qualifying for the Home Accessibility Tax Credit can also be claimed as a medical expense. Starting in 2026, these expenses will generally need to be claimed under only one provision and cannot be double-counted. Individuals planning eligible renovations may wish to take advantage of the current rules before this change takes effect.
The updated AMT rules that took effect in 2024 continue to apply. These include a higher minimum tax rate, modified calculation for adjusted taxable income affecting foreign tax credits and minimum tax carryovers, and limited value on most non-refundable tax credits.
Canada Training Credit (CTC) Eligible taxpayers aged 26 to 65 can claim this refundable tax credit to cover a portion of eligible tuition and fees for training or courses to enhance their skills.
Canada Caregiver Credit (CCC) This non-refundable tax credit supports individuals caring for family members or dependents with a physical or mental impairment. The amount varies based on the dependent’s relationship, net income, and circumstances.
Child Care Expenses Child care expenses, such as daycare, nursery schools, day camps, and boarding schools, are deductible if incurred to enable a parent or guardian to work, pursue education, or conduct research.
Disability Tax Credit (DTC) The DTC provides a non-refundable tax credit for individuals with disabilities or their caregivers to reduce the amount of income tax payable. For 2025, the disability amount is $10,138. Applicants must have a certified disability lasting at least 12 months. The expenses eligible for the disability supports deduction have also been expanded for 2025.
Moving Expenses Deductible moving expenses include transportation and storage costs, travel expenses, temporary living costs, and incidental expenses incurred when relocating at least 40 kilometers closer to a new work location, educational institution, or business location.
Interest Paid on Student Loans Interest paid on eligible student loans can be claimed as a non-refundable tax credit. The loans must be under federal, provincial, or territorial student loan programs.
Donations and Gifts Donations made to registered charities or other qualified organizations qualify for non-refundable federal and provincial tax credits. Typically, eligible amounts up to 75% of net income can be claimed. Note: due to the Canada Post strike in late 2024, eligible donations made in the first two months of 2025 can also be claimed on a 2024 return.
GST/HST Credit The GST/HST credit is a quarterly refundable payment designed to offset the impact of sales tax on low to moderate-income individuals and families. Eligibility is automatically assessed based on the annual tax return.
RRSP Contributions The maximum RRSP contribution for 2025 has increased to $32,490 (up from $31,560 in 2024), based on 18% of the previous year’s earned income. The TFSA annual contribution limit remains at $7,000 for 2025.
First Home Savings Account (FHSA) Contributions of up to $8,000 per year (lifetime limit of $40,000) are tax-deductible, grow tax-free, and qualifying withdrawals for a first home purchase are also tax-free. The FHSA can be used alongside the Home Buyers’ Plan, which maintains a withdrawal limit of $60,000.
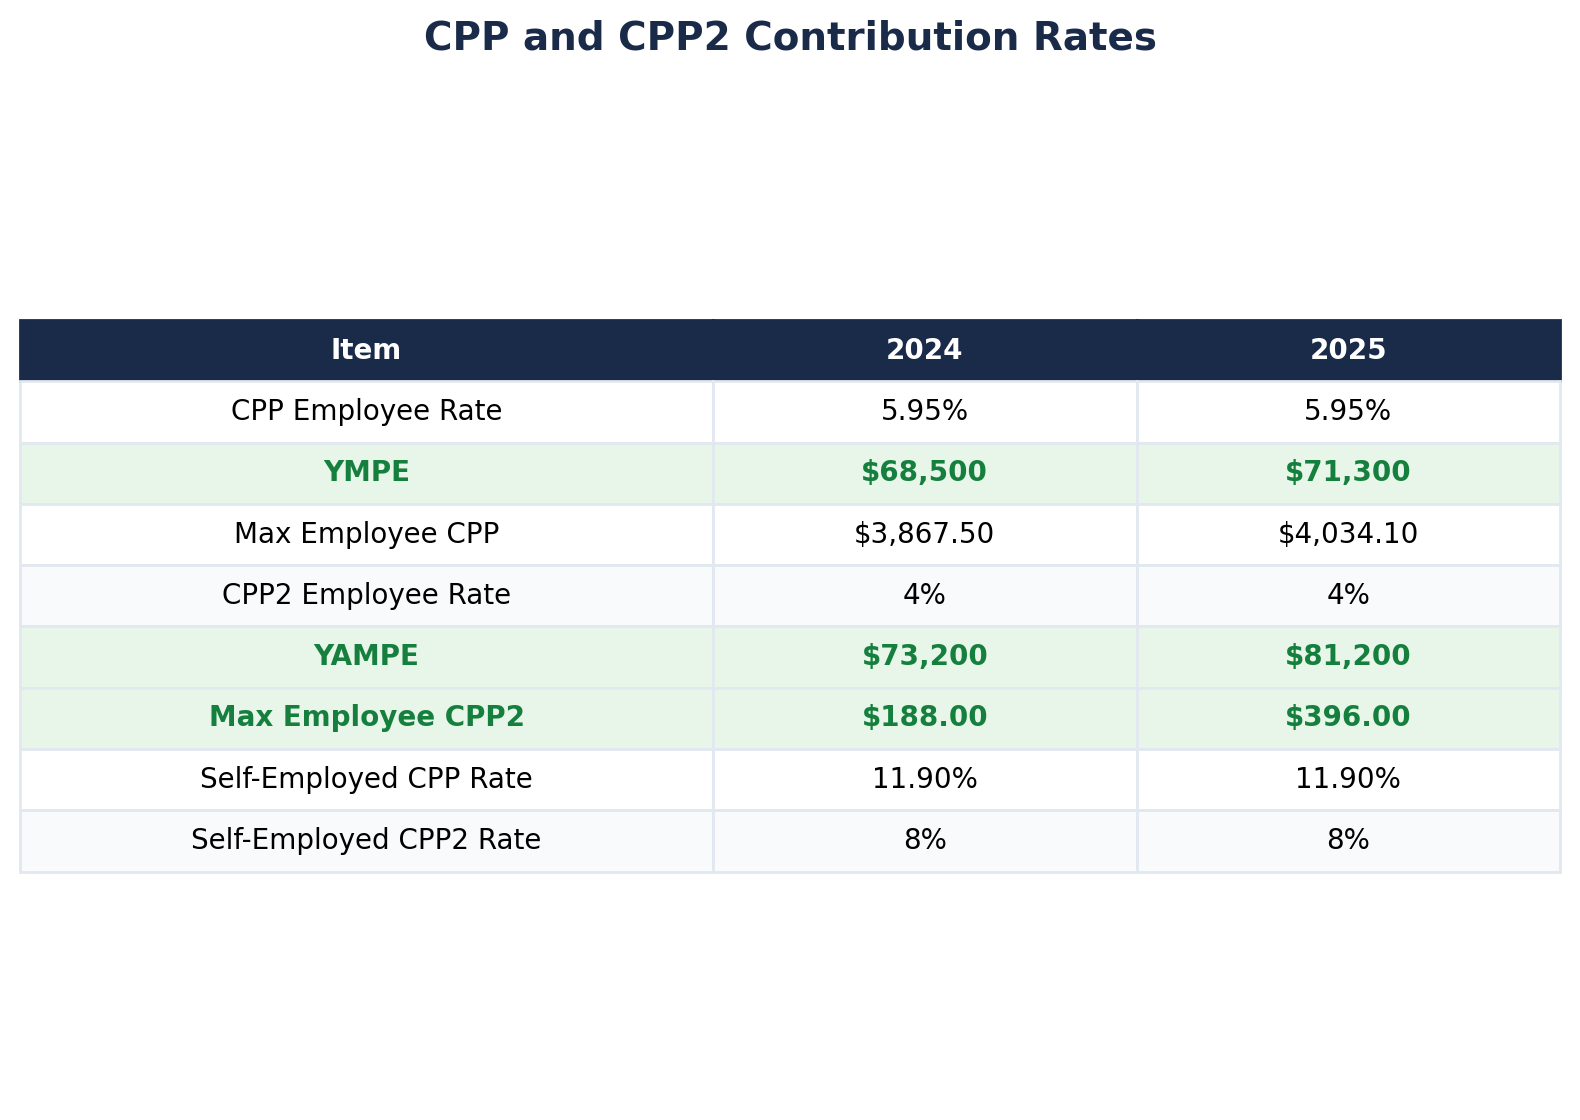
Self-employed individuals pay both the employee and employer portions of CPP, for a combined rate of 11.90% on earnings up to the YMPE ($71,300). For CPP2, the self-employed rate is 8% on earnings between $71,300 and $81,200, with a maximum CPP2 contribution of $792.
Tax Return Deadline: June 15, 2026.
Balance due must be paid by April 30, 2026.
Report income on a calendar-year basis for sole proprietorships and partnerships.
Reporting rules require platform operators to collect and report seller information to the CRA. If income is earned through a digital platform, it is important to ensure it is properly reported.
Filing season for 2025 returns opens February 23, 2026. With a lower federal tax rate, increased contribution limits, and several eliminated credits and taxes, reviewing these changes before filing can help maximize savings and avoid surprises. The CRA is also no longer mailing paper tax packages, so returns and forms are available online at canada.ca or by calling 1-855-330-3305.
Sources
Canada Revenue Agency. “Personal income tax: What’s new for 2025.” – Canada.ca – https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/about-your-tax-return/tax-return/completing-a-tax-return/whats-new.html
Canada Revenue Agency. “Important changes to the 2025 income tax package.” – Canada.ca – https://www.canada.ca/en/revenue-agency/news/newsroom/tax-tips/tax-tips-2025/important-changes-2025-income-tax-package.html
Canada Revenue Agency. “Maximum Pensionable Earnings and Contributions for 2025.” – Canada.ca – https://www.canada.ca/en/revenue-agency/news/newsroom/tax-tips/tax-tips-2024/canada-revenue-agency-announces-maximum-pensionable-earnings-contributions-2025.html
Canada Revenue Agency. “Basic Personal Amount.” – Canada.ca – https://www.canada.ca/en/revenue-agency/programs/about-canada-revenue-agency-cra/federal-government-budgets/basic-personal-amount.html
Canada Revenue Agency. “Tax rates and income brackets for individuals.” – Canada.ca – https://www.canada.ca/en/revenue-agency/services/tax/individuals/frequently-asked-questions-individuals/canadian-income-tax-rates-individuals-current-previous-years.html
“Budget 2025 – Tax Measures” (Home Accessibility Tax Credit change) – https://budget.canada.ca/2025/report-rapport/tm-mf-en.html
The opinions expressed are those of the author and not necessarily those of CI Assante Wealth Management Ltd. This material is provided for general information and the opinions expressed and information provided herein are subject to change without notice. Every effort has been made to compile this material from reliable sources however no warranty can be made as to its accuracy or completeness. Before acting on the information presented, please seek professional financial advice based on your personal circumstances.


Staying informed about financial limits and government benefits is essential for effective planning. The 2026 Canada Money Facts infographic provides a clear snapshot of key savings limits and retirement benefits, including TFSA, RRSP, FHSA, RESP, CPP, and OAS.
Here’s what you need to know for 2026.
The 2026 TFSA contribution limit is $7,000, bringing the cumulative contribution room to $109,000 for individuals who have been eligible since the TFSA was introduced in 2009 and have never contributed.
It’s important to note that total TFSA room depends on personal circumstances. Eligibility begins at age 18 or 19, depending on the province, and newcomers to Canada accumulate room only from the year they become residents. If you became eligible after 2009, your cumulative limit will be lower based on the years you qualified.
The TFSA remains one of the most flexible savings tools available, allowing investments to grow tax-free and withdrawals to be made without triggering tax.
For 2026, the RRSP contribution limit is $33,810, calculated as 18% of earned income from the prior year, up to the annual maximum. To fully maximize RRSP contributions for 2026, an individual would need prior-year earned income of approximately $187,833.
RRSPs continue to be a cornerstone of retirement planning, offering tax-deductible contributions and tax-deferred growth, which can be especially valuable during higher-income earning years.
The FHSA annual contribution limit remains $8,000 in 2026, with a cumulative contribution limit of $32,000.
As with previous years, FHSA eligibility begins at the age of majority (18 or 19, depending on the province), and contributions can only be made once the account is opened. Since the FHSA was introduced in 2023, not everyone will have access to the full cumulative room.
FHSA contributions are tax-deductible, and qualifying withdrawals for a first home purchase are tax-free, making this account a powerful planning tool for first-time homebuyers.
RESP limits remain unchanged in 2026:
Lifetime contribution limit: $50,000 per beneficiary
Annual Canada Education Savings Grant (CESG): up to $500
Lifetime CESG maximum: $7,200
RESPs continue to be an effective way to save for a child’s post-secondary education while benefiting from government grants and tax-deferred growth.
CPP benefit amounts increase for 2026:
Maximum CPP retirement benefit: $18,091 annually
Maximum CPP disability benefit: $20,894 annually
Actual CPP payments depend on an individual’s contribution history and the age at which benefits begin, but these figures provide a useful benchmark for planning purposes.
OAS payments for January 2026 are estimated at:
Ages 65–74: up to $8,907 annually
Ages 75+: up to $9,798 annually
OAS is subject to a clawback for higher-income retirees. In 2026, the clawback begins when 2025 net income exceeds $93,454. Full clawback thresholds are approximately $152,062 for ages 65–74 and $157,923 for ages 75 and over. OAS benefits are reduced by 15% of income above the threshold.
This 2026 infographic is designed as a quick reference to help Canadians stay informed and make confident planning decisions. Whether you’re maximizing registered accounts, preparing for retirement income, or saving for a home or education, understanding these updated limits helps ensure you’re making the most of available opportunities.
Staying proactive and informed in 2026 can make a meaningful difference in your long-term financial success.
Sources:
TFSA contribution limits: https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/tax-free-savings-account.html
RRSP contribution limits: https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/rrsps-related-plans.html
First Home Savings Account: https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/first-home-savings-account.html
Registered Education Savings Plan: https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/registered-education-savings-plans-resps.html
Canada Pension Plan: https://www.canada.ca/en/services/benefits/publicpensions/cpp/payment-amounts.html
Old Age Security: https://www.canada.ca/en/services/benefits/publicpensions/cpp/old-age-security/payments.html
– h2.1

On February 17, 2026, the B.C. government released its 2026 budget, projecting deficits of $9.6 billion for 2025–26 and $13.3 billion for 2026–27. The plan raises revenue through income tax increases, broader PST, and property tax changes. Most people will notice impacts in four areas: income tax, sales tax on services, property taxes, and family/volunteer benefits.
Starting 2026, B.C.’s lowest tax rate rises to 5.6% from 5.06% on the first $50,363 of income. Basic credits (personal amount, age amount) use the same higher rate.
This affects nearly everyone—workers and retirees alike—with a small but noticeable provincial tax bump on 2026 returns. Top combined federal/B.C. rates stay the same: 53.5% on ordinary income, 26.75% on capital gains.
From 2027–2030, indexation of brackets and credits freezes. Rising incomes will push more into higher brackets, quietly raising taxes over time.
Takeaway: Maximize RRSP/TFSA contributions, income splitting, and timing of withdrawals/bonuses.
From October 1, 2026, PST applies to:
Accounting/bookkeeping
Architectural/engineering/geoscience services (30% of price)
Strata/rental property management
Non-residential real estate commissions
Security/private investigation
Exemptions end for clothing patterns/yarn/fabrics, clothing repairs, basic cable, and landline/toll-free phone services.
Households face higher strata fees, renovation costs, and utility bills. Businesses see added service expenses.
Takeaway: Update 2026–27 budgets; business owners, review pricing/contracts.
Higher school tax on homes over $3M
Rural property taxes rise (tied to GDP growth) from 2026
$200 northern/rural homeowner benefit ends Jan 1, 2027
Speculation & Vacancy Tax to 4% from 3% (2027+) for foreign/untaxed owners
High-value, rural, or vacant property owners face higher carrying costs. Non-residents may rethink holding underused homes.
Takeaway: Review property plans.
B.C. Family Benefit disability supplement: up to $6,000/child (from July 2027), tied to federal DTC, phases out above $50K family income
Tax reduction credit: max $690 (from $575) if income under $25,570
Volunteer firefighter/search & rescue credit: $6,000 (doubled) from 2026
Takeaway: Check Disability Tax Credit eligibility; ensure credits are claimed.
These changes add up: small income tax hikes, broader PST, targeted property increases, plus select benefits.
If you’re wondering how these changes will affect your taxes or your long-term plans, let’s review your situation together and identify any adjustments that could keep you on track.
Sources: Province of British Columbia. Budget 2026: Stronger Together. Ministry of Finance, 17 Feb. 2026, www.bcbudget.gov.bc.ca/2026/.
The opinions expressed are those of the author and not necessarily those of CI Assante Wealth Management Ltd. This material is provided for general information and the opinions expressed and information provided herein are subject to change without notice. Every effort has been made to compile this material from reliable sources however no warranty can be made as to its accuracy or completeness. Before acting on the information presented, please seek professional financial advice based on your personal circumstances. CI Assante Wealth Management Ltd. is a Member of the Canadian Investor Protection Fund and the Canadian Investment Regulatory Organization.

Building a retirement plan in your final working decade feels a lot different than it did in your 30s. Back then, it was just about “saving.” Now, it’s about coordination. You are no longer just throwing money into a pot; you’re building the engine that will provide your paycheck for the next 30 years.
Think of this stage as your “Strategic Pivot.” You likely have the highest earnings of your life, but you also have the shortest timeline to recover if things go sideways. Here is how to organize your finances.
At this stage, where you put your next dollar is just as important as how much you’re saving. You want to fill these buckets in a way that gives you the most flexibility later.
Many people are surprised by what the government actually provides. These 2026 numbers help you find your “floor” so you know exactly how much your personal savings need to cover.
The CPP retirement pension is a monthly, taxable benefit designed to replace part of your income when you retire.
OAS is a residency-based benefit available starting at age 65.
When we put these two together, here is what the 2026 government baseline looks like:
Knowing these totals allows us to calculate the exact “gap” your personal investments need to fill to maintain your lifestyle.
You’ve worked too hard to let a health curveball derail your plan. At this stage, insurance isn’t an “extra”—it’s a defensive asset that transfers risk away from your savings.
The numbers above are a great starting point, but they only tell half the story. The real work begins when we bridge the gap between the government “floor” and the lifestyle you’ve envisioned for yourself.
Does your current plan feel like a collection of separate pieces, or a coordinated engine? If you’re ready to see how these 2026 rules apply specifically to your income and your goals, let’s connect.
Disclaimer: Coreplan Wealth Strategies is a Branch of CI Assante Wealth Management Ltd. The opinions expressed are those of the author and not necessarily those of CI Assante Wealth Management Ltd. Please contact them at (604) 434-4960 or visit https://coreplan.net/ to discuss your particular circumstances prior to acting on the information above. Insurance products and services are provided through Assante Estate and Insurance Services Inc. and Yousofi Financial Services Inc.. CI Assante Wealth Management Ltd. is a Member of the Canadian Investor Protection Fund and the Canadian Investment Regulatory Organization.
This article is for informational purposes only and does not constitute specific legal, tax, or financial advice. Figures are based on 2026 government thresholds and are subject to change. Insurance products are subject to eligibility, medical underwriting, and policy terms. Always consult with a qualified professional before making significant financial decisions.
Sources


Welcome to our 2026 financial calendar!
This calendar is designed to help you keep track of important financial dates and deadlines, such as tax filing and government benefit distribution. You can bookmark this page for easy reference or add these dates to your personal calendar so you don’t miss any important financial obligations.
If you need help with your taxes, 2025 income tax packages will be available starting January 20, 2026. Don’t wait until the last minute to get started on your tax return – make an appointment with your accountant so you’re ready when tax season arrives.
On January 1, 2026, the contribution room for your Tax-Free Savings Account (TFSA) opens again. The TFSA dollar limit for 2026 is $7,000.
For those who are eligible, the contribution room for your:
Registered Retirement Savings Plan (RRSP)
First Home Savings Account (FHSA)
Registered Education Savings Plan (RESP)
Registered Disability Savings Plan (RDSP)
will also be available for the 2026 calendar year.
For your Registered Retirement Savings Plan (RRSP) contributions to be eligible for the 2025 income tax year, you must make them by:
March 2, 2026
Contributions made after this date will generally count toward your 2026 tax return.
GST/HST credit payments will be issued on:
January 5
April 2
July 3
October 5
Canada Child Benefit payments will be issued on:
January 20
February 20
March 20
April 20
May 20
June 19
July 20
August 20
September 18
October 20
November 20
December 11
The government will issue Canada Pension Plan (CPP) and Old Age Security (OAS) payments on the following dates:
January 28
February 25
March 27
April 28
May 27
June 26
July 29
August 27
September 25
October 28
November 26
December 22
The Bank of Canada will make interest rate announcements on:
January 28
March 18
April 29
June 10
July 15
September 2
October 28
December 9
For most individuals, April 30, 2026 is the last day to:
File your 2025 personal income tax return, and
Pay any balance owing on your 2025 taxes.
This is also generally the filing deadline for final returns if death occurred between January 1 and October 31, 2025.
If death occurred between November 1 and December 31, 2025, the filing deadline for the final return is six months after the date of death (which will fall between May 1 and June 30, 2026).
If you or your spouse/common-law partner are self-employed:
The filing deadline for your 2025 tax return is June 15, 2026.
Any tax payments owing are still due by April 30, 2026.
Filing later than these dates may result in interest and penalties.
The final contribution deadline for the 2026 calendar year for the following accounts is December 31, 2026:
Tax-Free Savings Account (TFSA)
First Home Savings Account (FHSA)
Registered Education Savings Plan (RESP)
Registered Disability Savings Plan (RDSP)
December 31, 2026 is also the deadline for:
Making 2026 charitable donations that you want to claim on your 2026 tax return.
Individuals who turn 71 in 2026 to:
Make their last contributions to their own RRSPs, and
Convert their RRSPs to RRIFs (or an annuity).
Please reach out if you have any questions or would like help planning around any of these dates.
Sources:
Canada Revenue Agency. Tax-Free Savings Account (TFSA), Guide for Individuals. RC4466 (E), Canada.ca, https://www.canada.ca/en/revenue-agency/services/forms-publications/publications/rc4466/tax-free-savings-account-tfsa-guide-individuals.html.
Canada Revenue Agency. “Registered Retirement Savings Plan (RRSP).” Canada.ca, https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/rrsps-related-plans/registered-retirement-savings-plan-rrsp.html.
Canada Revenue Agency. “Registered Education Savings Plans (RESPs).” Canada.ca, https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/registered-education-savings-plans-resps.html.
Canada Revenue Agency. “First Home Savings Account (FHSA).” Canada.ca, https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/first-home-savings-account.html.
Canada Revenue Agency. “GST/HST Credit – Payment Dates.” Canada.ca, https://www.canada.ca/en/revenue-agency/services/child-family-benefits/gst-hst-credit/payment-dates.html#toc1.
Canada Revenue Agency. “Benefit Payment Dates.” Canada.ca, https://www.canada.ca/en/revenue-agency/services/child-family-benefits/benefit-payment-dates.html.
Canada. “Benefit Payment Dates Calendar.” Canada.ca, https://www.canada.ca/en/services/benefits/calendar.html.
Bank of Canada. “Bank of Canada Publishes 2026 Schedule for Policy Interest Rate Announcements and Other Major Publications.” Bank of Canada, https://www.bankofcanada.ca/2025/08/bank-canada-publishes-2026-schedule-policy-interest-rate-announcements-other-major-publications/.
Canada Revenue Agency. “Important Dates – Individuals.” Canada.ca, https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/important-dates-individuals.html.
Canada Revenue Agency. “Important Dates for RRSPs, RRIFs, and RDSPs.” Canada.ca, https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/rrsps-related-plans/important-dates-rrsp-rrif-rdsp.html.
CI Assante Wealth Management Ltd. operates as CI Assante Wealth Management, a dual-registered firm offering investment, mutual fund, and exempt-market products and services.
Wealth Planning services may be provided by an accredited advisor of CI Assante Wealth Management or CI Assante Private Client (a division of CI Private Counsel LP) and in some cases, by a non-affiliated third party. Insurance products and services are offered through Assante Estate and Insurance Services Inc.
CI Assante Wealth Management Ltd. is a member of the Canadian Investment Regulatory Organization and Canadian Investor Protection Fund.

